
Rebuilding financial stability after a divorce is a significant undertaking, and thoughtful financial planning for divorced women can help you regain control and confidence during this transition. From reassessing your budget to rebuilding credit, a clear plan makes this new chapter more manageable.
What is Financial Planning for Divorced Women?
Financial planning for divorced women involves reassessing your income, expenses, assets, and goals to build a stable financial foundation independently. This often includes updating budgets, understanding settlement terms, rebuilding or establishing individual credit, and revisiting long-term goals like retirement savings.
Benefits of Proactive Financial Planning After Divorce
- Restored financial confidence: A clear plan helps you feel more in control during a challenging transition.
- Protected long-term security: Proactive planning helps ensure retirement and savings goals stay on track independently.
- Improved credit health: Understanding your credit situation helps you build strong independent credit history.
- Realistic budgeting: Reassessing your finances ensures your new budget reflects your actual independent circumstances.
How to Approach Financial Planning for Divorced Women
Step 1: Gather and Review All Financial Documents
Collect account statements, tax returns, and settlement documents to get a complete picture of your financial situation.
Step 2: Create a New Independent Budget
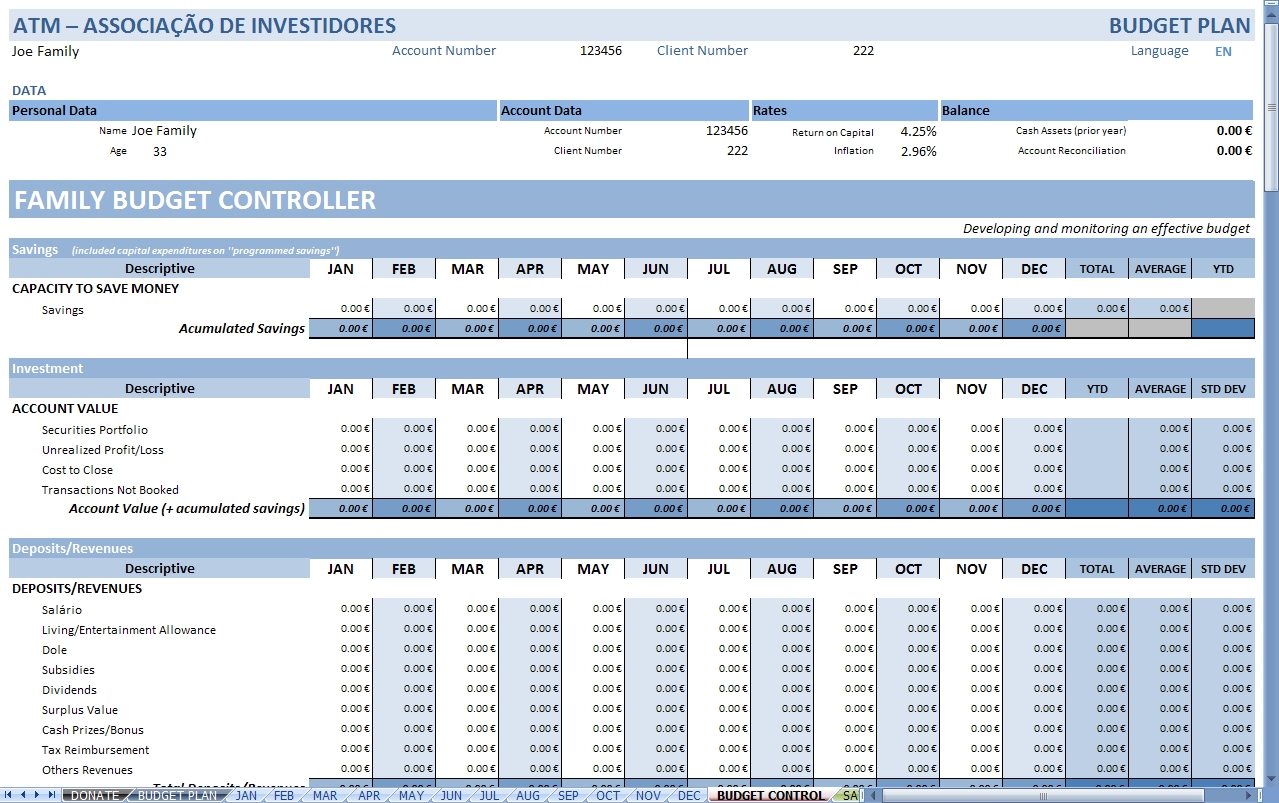
Build a budget reflecting your individual income and expenses, accounting for any changes from the divorce settlement.
Step 3: Update Beneficiaries and Estate Documents
Review and update life insurance, retirement accounts, and wills to reflect your new circumstances.
Common Mistakes to Avoid
- Not reviewing and updating beneficiary designations after divorce.
- Ignoring credit accounts that may still be jointly held.
- Delaying retirement account rollovers or updates required by the settlement.
- Not consulting a financial advisor familiar with post-divorce planning.
- Making major financial decisions too quickly without a clear long-term plan.
Tips From Experts
- Close or separate joint credit accounts as soon as your settlement allows.
- Establish credit in your own name if you haven't already.
- Consult a Certified Divorce Financial Analyst for specialized guidance.
- Review your tax filing status changes and their financial implications.
- Build an emergency fund as a priority during this transition period.
Frequently Asked Questions
Should I hire a financial advisor after divorce?
Many women benefit from working with an advisor, especially one specializing in post-divorce financial planning.
How do I separate joint credit accounts?
Contact creditors directly to close joint accounts or remove your name, following your settlement terms.
What should I do with retirement accounts after divorce?
Follow your settlement's Qualified Domestic Relations Order guidance for splitting retirement assets properly.
How can I rebuild my credit independently?
Open accounts in your own name and maintain consistent, on-time payments to build independent credit history.
When should I update my will after divorce?
As soon as possible, to ensure your estate plan reflects your current wishes and circumstances.
Conclusion
Thoughtful financial planning for divorced women helps you rebuild stability and confidence as you move into this new chapter. Review your finances thoroughly, create an independent budget, and don't hesitate to seek professional guidance.
For more on financial wellness, see our guide on osteoporosis prevention and treatment, and learn more at ConsumerFinance.gov.
This article is for general informational purposes only and is not financial or legal advice.
Comments
Post a Comment